How to Set Aside Money for Repairs Without Guessing
A flexible way to make room for occasional vehicle needs without turning every unfamiliar sound into a financial forecast.
Setting aside money for car repairs doesn’t need to be a guessing game. The most reliable approach separates what you know is coming from what might happen occasionally, turns simple records into forecasts, and treats the reserve as a working tool rather than an unexamined lump sum. That mindset keeps you prepared without turning maintenance into a mystery or a hobby of always imagining worst-case scenarios.
Start by thinking in two buckets: predictable service items you can calendar and one-off or infrequent repairs that arrive on their own schedule. Using past invoices and a few targeted questions about how and where you drive gives you far better information than gut feel. That information helps you set a recurring transfer you can live with and revisit when reality changes.
This article walks through four practical steps: separating routine from occasional costs, choosing a revisit-able starting amount, relying on records instead of assumptions, and keeping the reserve proportionate to your needs. Each section includes concrete record prompts and decision questions so you can build a simple, honest reserve without guessing.
In this article
Separate routine from occasional
Routine items are those you expect to budget for on a schedule: oil or fluid service, filters, windshield wipers, bulbs, minor tire repairs, and similar calendar- or mileage-driven work. Occasional items are repairs or replacements that arrive irregularly: a water pump, alternator, suspension components, or repairs after an incident. Ask yourself: which expenses recur at a steady interval, and which have shown up unpredictably in the past five years?
A practical way to manage both is to maintain two distinct buckets—one for recurring maintenance and one for occasional or major repairs. For the recurring bucket, sum invoices over the past 12 months and divide into monthly targets. For the occasional bucket, list out larger items from the last several years and annualize them (divide the cost of a replacement by the number of years between replacements). Keep date, odometer, item, cost, and who did the work so you can see patterns instead of guessing. Red/flashing alerts, sudden/persistent behavior changes, or uncertainty about safe travel should be evaluated promptly by a qualified professional.
Choose a starting amount you can revisit
Pick a practical monthly transfer that reflects your records and cash flow rather than trying to hit a theoretical target on day one. Use the annualized totals from your two buckets as a guide and choose a round amount that fits your budget. Treat this number as provisional: plan to review it after six to twelve months and after any unusually large spend so you can increase, decrease, or reallocate funds based on actual spending.
Decide on where to hold the money with ease of access in mind: a labeled savings subaccount, an envelope in your household budget, or a distinct line in a budgeting app so transfers and spending are transparent. Automate transfers where possible so the habit sticks, and document the purpose so a partner or future owner understands what the money is for. This is a planning technique, not financial advice — use your records and priorities to pick a level you can sustain and revisit regularly.
Use records instead of assumptions
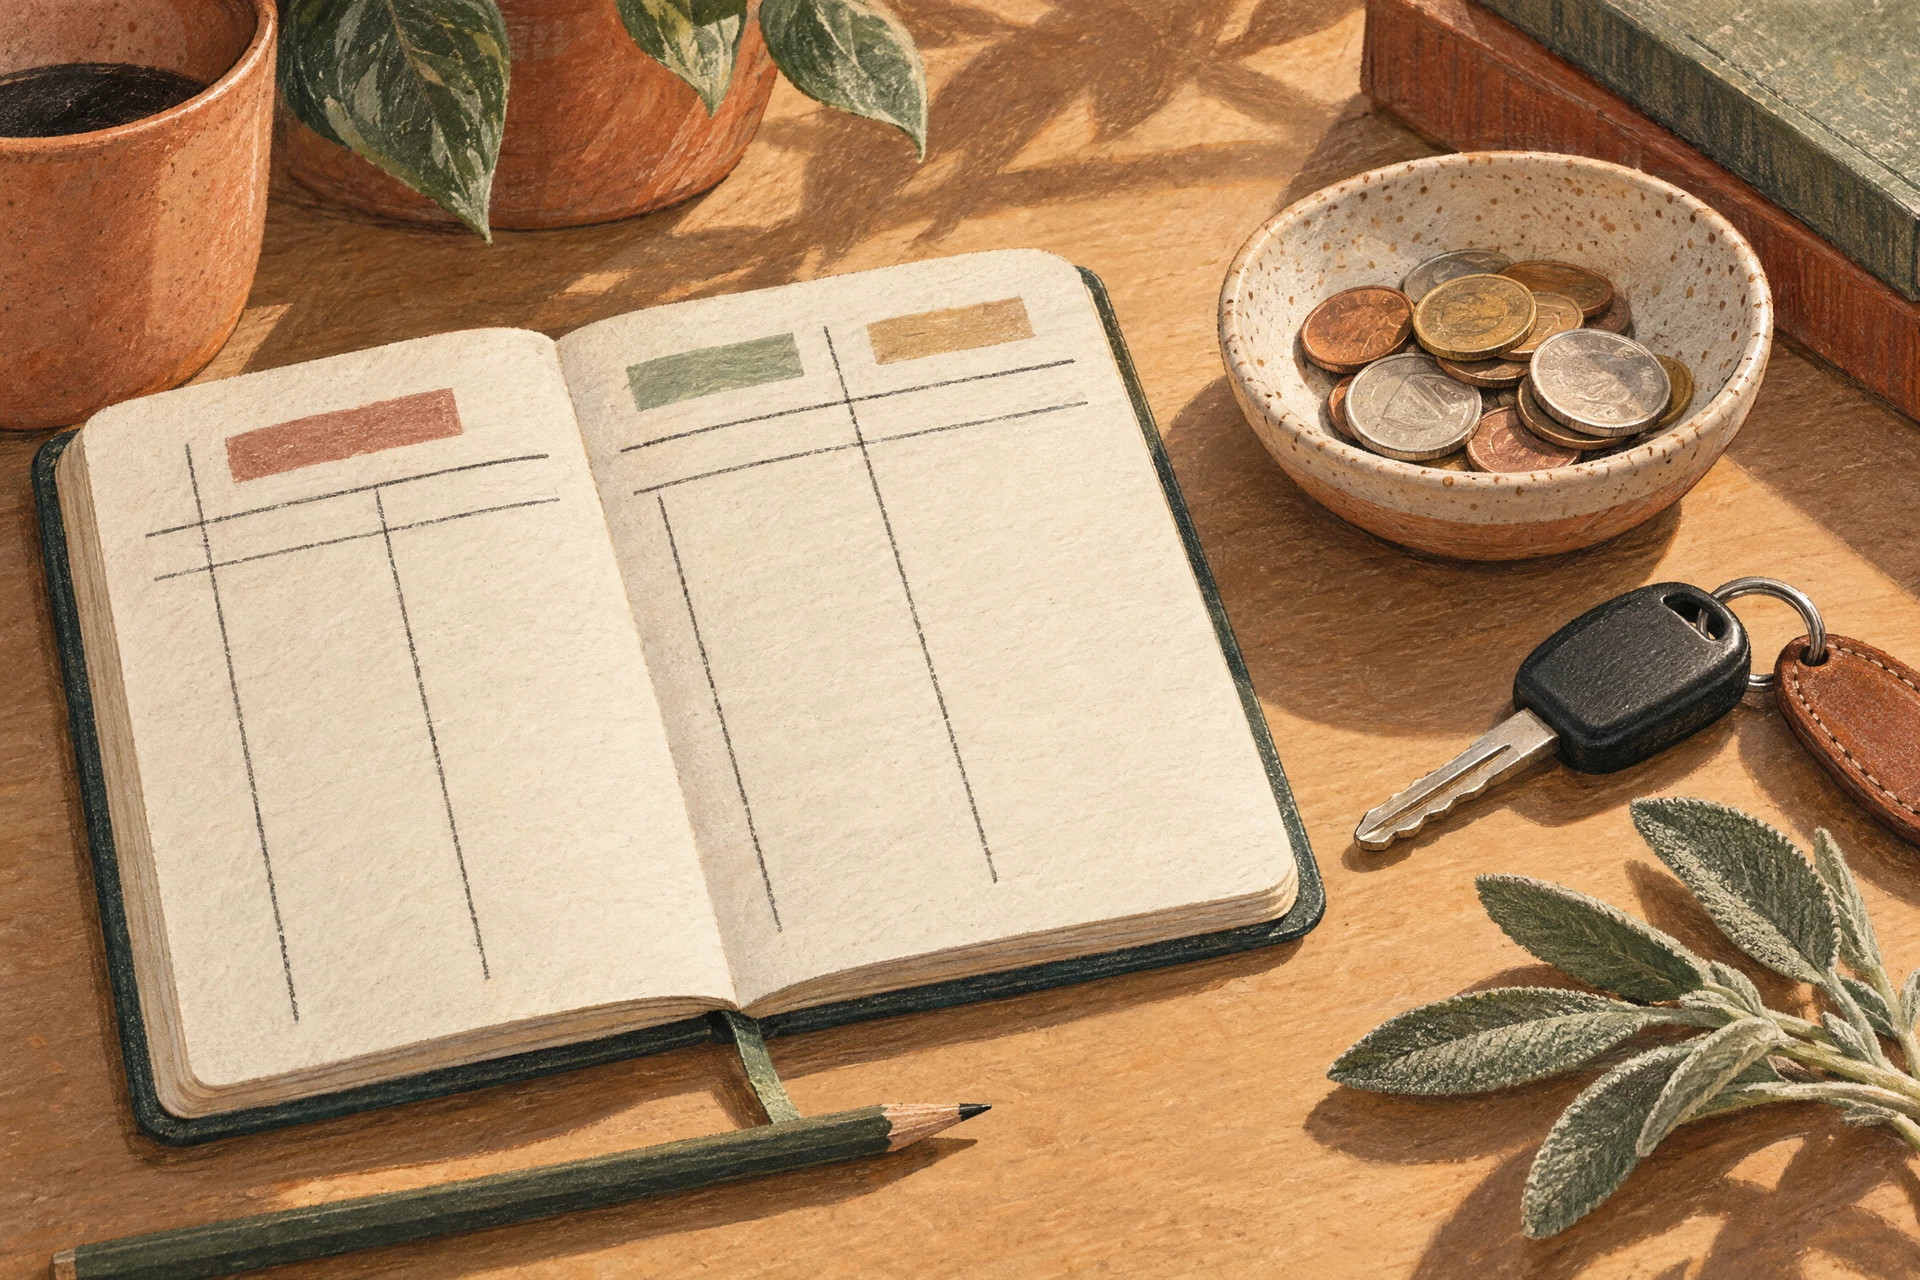
Build a simple repair ledger and commit a few minutes after each visit to record essential facts: date, odometer reading, a concise description of the work, parts cost, labor cost, warranty terms, and a photo or scanned receipt. If a shop gives an estimated life span for a part, jot that down. These entries let you answer practical forecasting questions: when are tires likely to need replacement, how long between brake-pad jobs for your driving style, and which shops give the best value on repeat items.
When you forecast, look at averages and also flag outliers. If a major repair occurred after an accident, treat it as a one-off in your occasional fund rather than letting it inflate your monthly transfer indefinitely. Conversely, if an item is showing shorter intervals than the owner’s manual suggested, increase the monthly amount and note questions to ask your mechanic. Use simple math—average intervals, divide costs by years, and keep a running total—so the reserve grows from facts rather than assumptions. Red/flashing alerts, sudden/persistent behavior changes, or uncertainty about safe travel should be evaluated promptly by a qualified professional.
Keep the reserve in perspective
A reserve should match your vehicle’s condition, your tolerance for downtime, and how quickly you can find trusted help. If you drive long distances daily or rely on a car for work, you may prefer a larger cushion or a separate short-term loan option for big jobs; if you have flexibility and access to a trusted shop, a smaller reserve that covers expected annualized costs plus a modest buffer may be more efficient. Ask: how long can I be without this vehicle, and how quickly can I access funds if a large job is required?
Review the reserve at regular intervals and when life changes—new commute, towing needs, or a planned road trip. If your record ledger shows rising costs or earlier-than-expected replacements, adjust your monthly transfer and the way you classify funds. Reserve money should be separate from emergency savings for household needs, and use it for planned or documented vehicle expenses. For complex or unclear repairs, seek multiple quotes and the advice of a qualified professional rather than relying on the reserve to justify a risky repair choice. Red/flashing alerts, sudden/persistent behavior changes, or uncertainty about safe travel should be evaluated promptly by a qualified professional.
Keep the next step useful
Setting aside repair money works best when it’s tied to records, split between routine and occasional needs, and treated as adjustable rather than fixed. Use the ledger prompts and decision questions in this article to pick a starting transfer you can live with, automate it, and revisit when real invoices tell a different story. If you encounter red or flashing alerts, sudden or persistent behavior changes, or are unsure whether a vehicle is safe to drive, have it evaluated promptly by a qualified professional.